


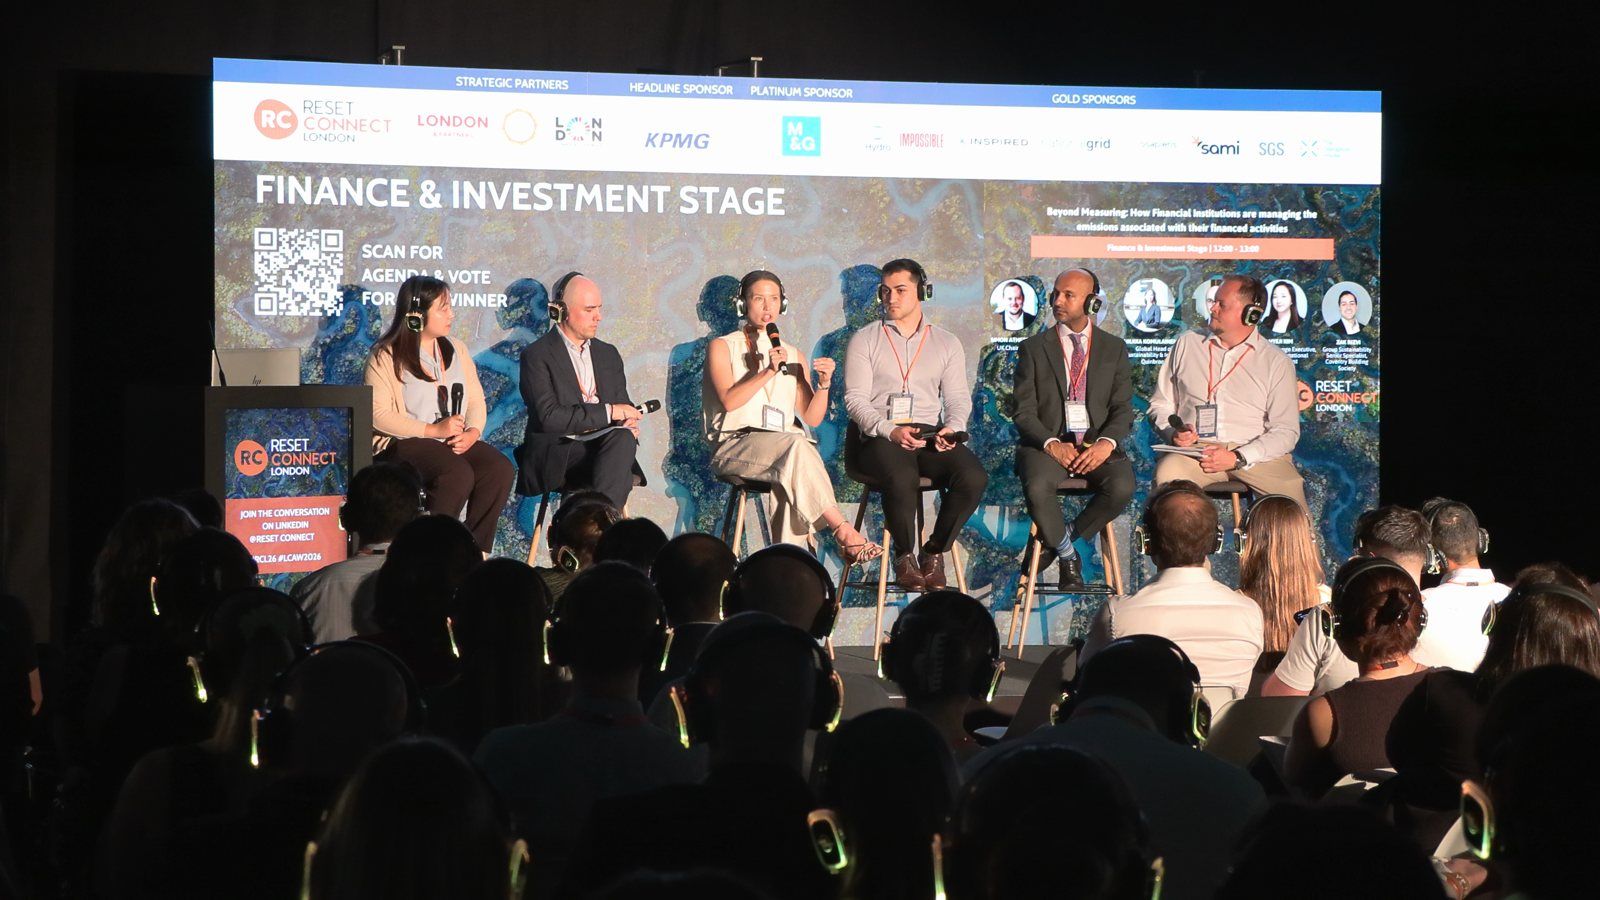
Beyond Measuring: How Financial Institutions are managing the emissions associated with their financed activities
Home | Blog | Beyond Measuring
Event Reset Connect London 2026
Date Tuesday 23 June 2026
Stage Finance & Investment Stage
Moderator Simon Atherton, Standard Life and UK Chair, PCAF
Speakers Hetal Patel, Standard Life. Zak Rizvi, Coventry Building Society and The Co-operative Bank. Hilkka Komulainen, Quinbrook. Ian Bhullar, UK Finance. Hyeji Kim, British International Investment.
Estimated read time 11 minutes
Quick Read Summary
When Coventry Building Society and The Co-operative Bank compared their mortgage portfolios, they found something that would be easy to miss in a disclosure. The two organisations used different methods to estimate emissions, even though their data quality scores were very similar. The comparison raised a question that ran through the panel at Reset Connect London 2026. What can financial institutions do with the numbers they have, and what do they need to understand before they act on them?
The answers differed by institution. An asset owner can use an emissions estimate to decide where to engage a company. A mortgage lender can use it to understand which customers a new proposition might serve. An infrastructure investor can bring emissions evidence into procurement and investment decisions before an asset is built.
Give the measurement a job
Simon Atherton of Standard Life framed the session around the shift from measuring financed emissions to managing them. A portfolio total can tell an institution where emissions are concentrated. The next step is to decide what that concentration means for the people who manage the portfolio, work with clients or design lending products.
The same figure can prompt different questions in different teams. An investment team might want to know whether a company has a credible transition plan. A relationship manager might want to understand which changes a client can make and what stands in the way. A reporting team may first need to explain the assumptions behind the estimate. The panel’s examples showed how those questions can make the inventory more useful. Each one gives an institution a reason to look more closely at a particular part of its book.
Atherton also introduced the panel as a conversation across several kinds of financial institution. That breadth matters to the question of ownership. The team producing the inventory can identify a concentration of emissions, while the people who know the borrower or investee are better placed to ask what is driving it. Bringing those teams together gives the institution a chance to turn an observation into an engagement question with a named owner and a follow-up date.
Consider what happens if an estimate suggests a company is responsible for a large share of a portfolio’s footprint. The investment team may first ask how much of the number comes from company reporting and how much is estimated. It can then decide whether to ask about a specific activity or about the company’s wider transition trajectory. The useful output of that discussion is a question the company can answer and the institution can return to.
Compare the methods behind the scores
Zak Rizvi described the work of comparing mortgage data as Coventry Building Society and The Co-operative Bank brought their organisations together. The portfolios looked comparable at first glance. They were in the same line of business and their data quality scores were similar. Comparing the underlying calculations revealed that the teams had arrived at those scores using different methods.
The Partnership for Carbon Accounting Financials, or PCAF, provides a common way to communicate the quality of the data used in a financed emissions estimate. A common scale gives teams a place to start. The comparison Rizvi described shows why an institution also needs the assumptions that sit behind it. If two teams take different approaches, knowing where they differ helps explain which parts of a combined portfolio can be compared consistently and where further work is needed.
That matters when a figure changes from one reporting period to the next. Better inputs, changes in the portfolio and changes in underlying emissions can all affect what is reported. An explanation of the method helps readers and internal teams work out which of those changes the number can support.
The comparison was particularly revealing because the work concerned mortgages on both sides. A difference between asset classes might be expected. Here, the difference surfaced when the teams put similar portfolios side by side. A useful reconciliation would start with the records each side uses, then compare how the calculation handles gaps and whether the same assumptions apply to equivalent groups of properties. The score is one part of that conversation. The calculation itself shows where the teams need to agree an approach.
A reporting team can also use that comparison to explain movements during integration. If one set of estimates changes when the two books move to a common method, the team can identify the effect of that change before drawing conclusions about the properties themselves. The same principle applies outside a merger. Comparing this year’s estimate with last year’s is easier when the institution can explain which inputs, boundaries and methods changed between the two calculations.
Use estimates to decide where to look closer
The Standard Life discussion drew a distinction between public and private assets. For public holdings, data vendors can make it easier to obtain emissions information and may supply a quality score alongside it. The work then shifts towards judging how credible the numbers are and whether they warrant closer engagement with a counterparty.
Private assets can present a different problem. A new project may have no emissions history of its own. The investor might need to use comparable projects or a sector average to build an initial estimate. That gives the investment team something to work with, provided the basis for comparison is clear and the estimate’s limitations travel with it.
The practical question is which uncertainty matters to a decision. For a project whose design is still taking shape, obtaining better information about one component may be more useful than refining a portfolio average. For an existing holding, the better question may be what the company can tell the investor about the emissions and the changes it expects to make.
Hetal Patel’s distinction between the public and private sides of the book also shows how differently the same question can start. With a public holding, a team can begin with the available data and decide whether to challenge an assumption or engage with the company. With a new private project, the first step may be finding a sensible comparator. A sector average can provide a starting point while leaving the investor with a clear question about what would make the project materially different from that average.
There is a timing implication for the investment committee. The information available when a project first comes forward may be different from what the team can obtain once its design, suppliers or operations are known. Recording the basis of the first estimate makes it possible to replace it later and explain why it moved. It also lets the team decide which piece of information is worth requesting before committing capital.
Distinguish emissions generated from emissions avoided
Hilkka Komulainen described how Quinbrook considers emissions as an investor that builds energy transition infrastructure. Her examples moved the discussion upstream, into the decisions that shape an asset. What equipment goes into the project? How emissions-intensive is that equipment to produce? What electricity would the project displace in the grid where it operates?
Those questions involve different kinds of evidence. Emissions generated by a project describe the footprint associated with building or operating it. Avoided emissions depend on a comparison with what would otherwise happen. A renewable asset’s estimated contribution can therefore depend on the generation it is assumed to replace.
Komulainen described using both perspectives in investment and procurement. Keeping them separate allows a team to see the trade-offs. It can examine an asset’s own footprint alongside the potential benefit of adding it to a particular electricity system, with the assumptions behind each calculation available for review.
Komulainen also described investors asking why the reported numbers fluctuate from quarter to quarter. She pointed to the project lifecycle. A period of construction can have a different emissions profile from a period when the asset is operating. An investor reading the figures needs that context to understand whether the movement reflects a new phase of work or a change that merits a closer look.
The panel also linked this evidence to the customer buying the project’s output. A prospective buyer may want to understand what the energy purchase contributes to its own renewable energy or emissions objectives. The investor has a different question about the asset and its return. Both benefit from seeing how the underlying estimates were made. That means spelling out the counterfactual for an avoided-emissions estimate and giving construction-related changes their own explanation when reporting the footprint.
Design mortgage propositions around different borrowers
Rizvi explained how a retail lender can use financed emissions at portfolio level. The analysis can show where to look when developing products and propositions. For example, a residential mortgage portfolio can include both homes occupied by their owners and homes rented out by landlords. Those groups may face different decisions about whether and how to improve a property.
An owner-occupier weighs the cost and disruption of work against the benefits in their own home. A landlord may have to consider how the work affects tenants, who pays the energy bills and whether improvements make sense across several properties. The same broad emissions category can therefore contain customers who need different forms of support.
That makes segmentation a useful bridge between measurement and product development. A lender can use the portfolio figures to identify where a proposition might make a difference, then ask what practical barriers customers in that group face. The panel described this as a use of portfolio insight in product design.
In the comparison Rizvi described, the landlord products had lower average attributed emissions than the owner-occupied group. He used that observation to explain why the lender wanted evidence behind the distinctions it made between groups. It is a finding about the portfolios he was discussing. A lender examining another portfolio would still need to establish what explains its own averages before drawing conclusions about where a product would help.
A product team can turn the comparison into a practical brief. Identify which customers have the ability and incentive to make improvements, then ask what would make a proposition useful to them. The data can help locate the groups worth speaking to. Conversations with those customers can reveal whether the barrier is access to finance, the timing of the work or something the lender’s product can do little to change.
Build the capability one portfolio at a time
The panel returned to the practical cost of trying to measure everything at once. Different asset classes need different inputs. Records may be missing or held in systems that do not make it easy to combine them. The closing discussion described reaching a point where attempting to estimate every part of the portfolio at the same time stopped being productive.
Working in stages makes it possible to choose an initial portfolio, learn where the records are weak and show management what better information could change. It also gives teams a reason to share what they learn. Atherton closed by encouraging people from financial institutions to engage with the UK PCAF chapter, observing that different organisations were encountering similar questions.
The closing discussion makes a case for showing management what the first round of work has achieved. A team can bring back an example of an estimate it could use, another where it hit a data gap and a decision that would benefit from better information. That gives management a basis for deciding where to invest in data or bring in the people who own the relevant systems.
Atherton’s invitation to the UK PCAF chapter followed directly from that experience. Teams can compare how they approached similar problems even when their books differ. The Coventry example illustrates what makes that exchange worthwhile. Hearing that another institution has a similar quality score is less revealing than understanding how it arrived at the number and what it used it for.
Practical Application
Choose one portfolio and one decision the emissions work should inform. A mortgage team might compare owner-occupied and buy-to-let segments before designing a proposition. An investment team might choose a holding where further engagement could clarify what is driving its emissions.
Record the source, method and data quality alongside the estimate. Ask what could move the number and which changes would affect the decision. Give the responsible team a way to record what it did with the result, whether that means asking for better data, speaking to a client or considering a different design. Review both the estimate and the action when the portfolio is next assessed.
At the first review, put the decision owner, estimate and next action in the same record. For example, a portfolio manager may decide that one company merits engagement because better operational data could change how the holding is assessed. In the next review, ask what was learned and whether it affected the decision. That closes the gap between the work of collecting emissions information and the work of managing a portfolio.
Key Takeaways
- Compare calculation methods before treating similar data quality scores as evidence of comparability.
- Use estimates to identify where better data or engagement could change a decision.
- Keep generated and avoided emissions separate and document the comparison used.
- Use portfolio-level findings to develop propositions for borrowers with different needs.
Quote of the Session
“Everybody is dealing with similar kind of topics and looking to do similar things.”
Simon Atherton, Standard Life and UK Chair, PCAF
Final Thoughts
The panel offered several ways to put a financed emissions inventory to work. The mortgage comparison showed how much can sit behind a quality score. The infrastructure examples showed how early in a project emissions information can inform a choice. In each case, the value of the measurement depends on whether the people making the decision can understand it and act on it.
Speakers
Simon Atherton, Climate and Investment Research Lead at Standard Life and UK Chair of PCAF, moderated the session.
Hetal Patel, Standard Life, contributed the asset-owner perspective.
Zak Rizvi, Group Sustainability Senior Specialist at Coventry Building Society and The Co-operative Bank, discussed mortgage portfolios and product development.
Hilkka Komulainen, Global Head of Sustainability and Impact at Quinbrook, discussed emissions in infrastructure investment and procurement.
Ian Bhullar, Director of Sustainability at UK Finance, brought the trade body perspective on the conditions needed for lenders and investors to support the transition.
Hyeji Kim, British International Investment, contributed the development finance perspective.
Watch Full Session